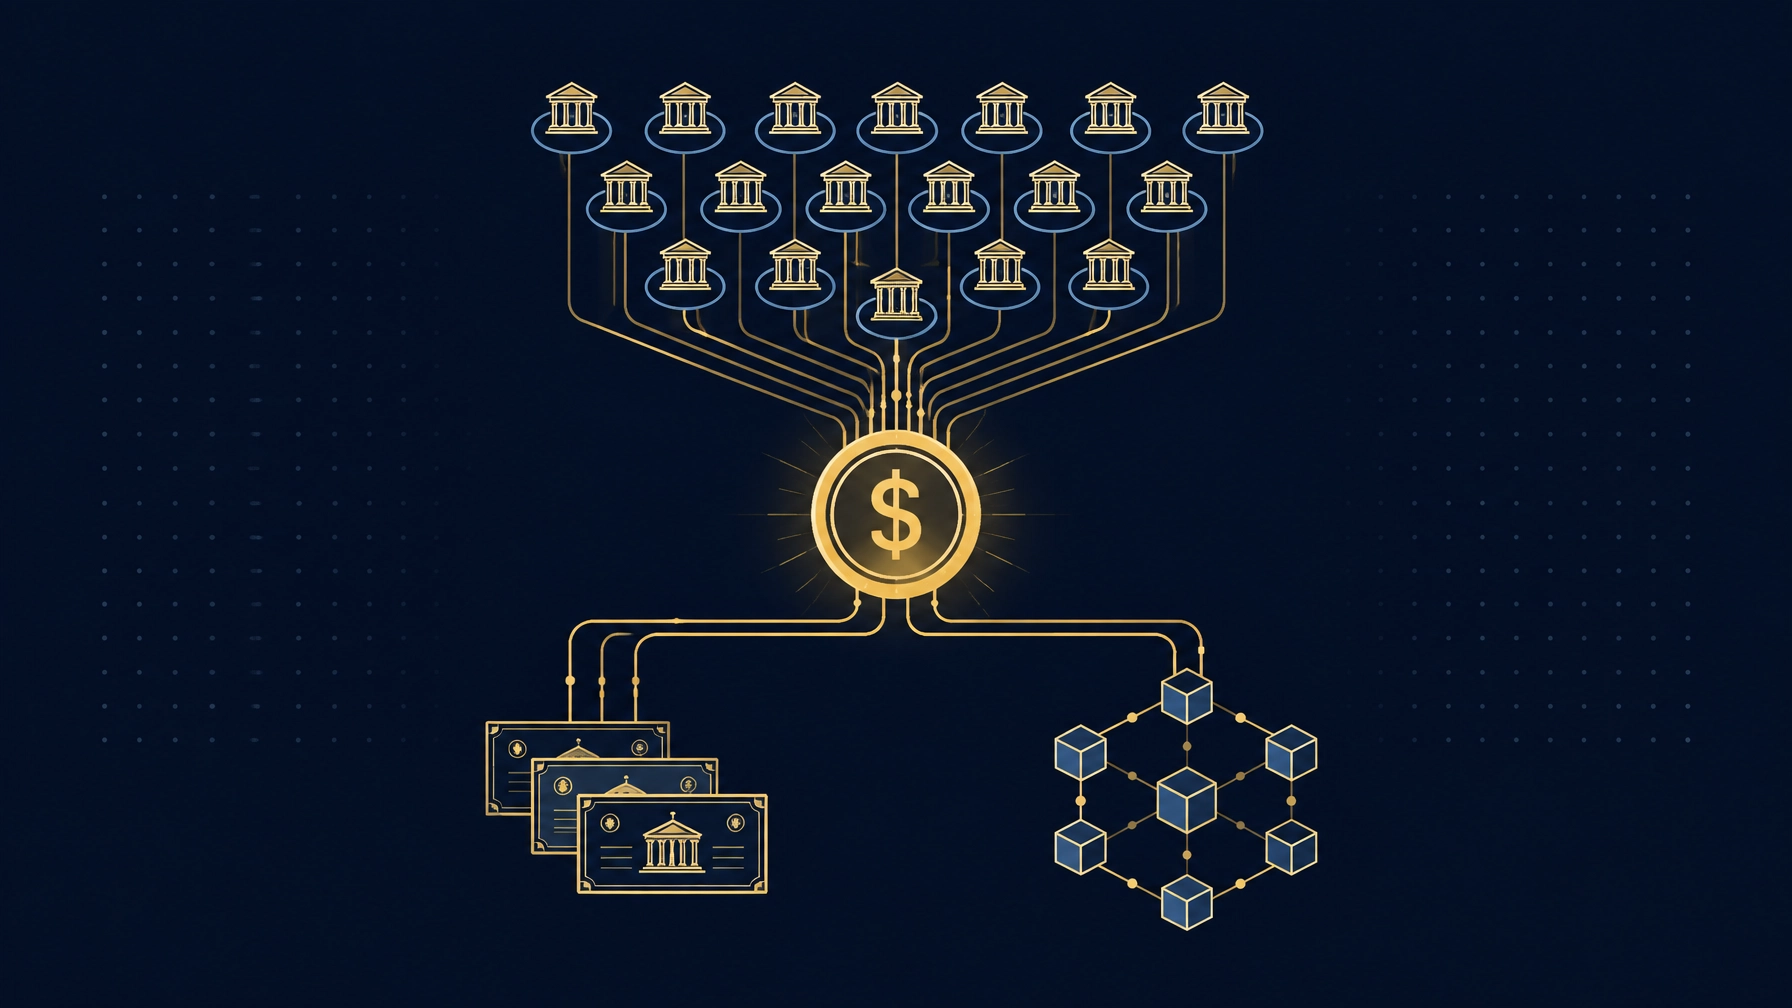
On September 1, twenty-one major financial institutions announced plans to create a new company and issue a dollar-denominated payment stablecoin in the first half of 2027. The company itself is expected to be formed in the second half of 2026. It has no public name yet. Neither does its coin. Its blockchain, reserve composition, and redemption mechanics remain undisclosed.[1]
That is the first fact. The second is the temptation to call it “collusion under the GENIUS Act.”
That may become a serious legal or economic question. It is not, however, what the statute says, and it is not what the press release established. The documented event is a coordinated joint venture among competitors. The interpretation: that this amounts to cartel behavior: is still an argument.
The better description, for now, is less theatrical and more revealing: private dollar plumbing wearing a statute.
The Coin Is Not the Fed
A central bank digital currency would be a direct liability of a central bank. The Trump administration’s January 2025 executive order expressly prohibited federal agencies from establishing, issuing, circulating, or promoting a U.S. CBDC while encouraging lawful, dollar-backed private stablecoins.[2]
The proposed 21-bank instrument belongs to the private category. It would be issued by a new company, backed by permitted reserves, and intended for use on public blockchain networks. It would not be a Federal Reserve liability, and it would not be a conventional bank deposit.[1][3]
That distinction is more than legal housekeeping. A Federal Reserve balance is central-bank money. A bank deposit is a commercial bank’s promise to you. A payment stablecoin is a private issuer’s promise to redeem a digital token for a fixed amount of monetary value. All three may be described casually as “dollars.” They are not the same claim.
The difference is the foundation beneath the building. Ignore it, and the façade becomes the analysis.
What GENIUS Actually Built
The Guiding and Establishing National Innovation for U.S. Stablecoins Act: GENIUS: was signed into law on July 18, 2025, as Public Law 119-27. Its core framework is scheduled to become effective on January 18, 2027, unless final implementing rules cause the statute to take effect earlier.[3][4]
The law creates three broad paths to become a permitted payment stablecoin issuer:
- A subsidiary of an insured depository institution, subject to approval by its primary federal regulator;
- A federally qualified issuer supervised through the federal framework; or
- A state-qualified issuer operating under a state regime that satisfies federal requirements.
The state route is not an escape hatch without a ceiling. State-qualified issuers above approximately $10 billion in outstanding stablecoin issuance must transition into the federal framework.[3][4]
The reserves are similarly constrained. They may include U.S. currency, Federal Reserve deposits, demand deposits at insured institutions, Treasury securities with a remaining maturity of 93 days or less, qualifying overnight Treasury-backed repurchase arrangements, and government money-market funds investing in permitted assets.[3][5]
The issuer cannot treat the reserve pool as a conventional lending base. The Act restricts pledging, rehypothecating, and reusing reserve assets except for narrowly defined liquidity and redemption purposes.[5] In ordinary language: the reserves are supposed to be a foundation, not a revolving door.
But the token itself is not insured. GENIUS does not make a stablecoin an FDIC-insured deposit, and it does not grant an issuer automatic access to a Federal Reserve master account.[6] If a holder is told that “dollar-backed” means “government-guaranteed,” the advertisement is doing more work than the statute permits.

The Yield Ban Is the Business Model
GENIUS prohibits permitted payment stablecoin issuers from paying holders interest or yield merely for holding the token.[5]
The reserve assets, however, can earn income. Treasury bills pay interest. Qualifying repo transactions generate returns. Government money-market funds produce income. The holder receives a digital dollar that does not pay yield; the issuer holds the assets that do.
This is not a side detail. It is the business model.
Circle’s 2025 filing shows how powerful that model can be: reserve income represented the overwhelming majority of the company’s revenue, generated from cash and short-duration assets backing its stablecoins.[7] Tether has likewise reported substantial exposure to U.S. Treasury bills and Treasury-backed instruments.[8]
The proposed consortium is therefore not merely building a faster payment token. It is positioning itself around a large pool of non-interest-bearing customer claims backed by interest-earning government assets.
That is the float.
The practical question is not whether the coin will be “free.” The practical question is who receives the coupon while the user receives the convenience. Under GENIUS, the answer is generally the issuer rather than the holder. Twenty-one balance sheets are not joining hands out of philosophical affection for distributed ledgers. They are seeking control of the customer relationship, the payment rail, and the reserve income attached to the float.
Two Rails, Not One
The banks are pursuing a two-rail strategy.
The first rail is the tokenized deposit. The Clearing House has described a bank-led initiative to move tokenized commercial bank money between institutions, connect blockchain activity to existing payment systems, and preserve the underlying banking framework. The official participant list (June 2026) includes JPMorgan Chase, Citi, Bank of America, Wells Fargo, BNY, HSBC, PNC, U.S. Bank, Truist, Santander, TD, and Regions.[9]
A tokenized deposit remains a deposit obligation of a bank. Its legal character comes from the bank’s balance sheet, not merely from the technology used to record it. The FDIC has emphasized that technology does not determine whether a qualifying bank deposit is insured, although stablecoin holders do not receive pass-through FDIC coverage simply because a stablecoin issuer holds insured-bank deposits as reserves.[6]
The second rail is the 21-bank stablecoin. JPMorgan's absence from that roster is conspicuous but not mysterious: its strategic emphasis has been tokenized deposits and JPM Coin, while several institutions — Citi, Bank of America, Wells Fargo, Santander, TD — appear on both maps, playing both rails at once.[1][9] JPMorgan has publicly said it is seeing “zero demand for deposit tokens” and has been reported (August 2026) to be evaluating its own stablecoin as that strategy evolves.[10][11]
The distinction matters for another reason. JPMorgan is also the institution that paid the largest precious-metals manipulation penalty on record: $920.2 million in September 2020, resolving CFTC, DOJ, and SEC actions over spoofing and manipulation in gold, silver, platinum, palladium, and U.S. Treasury futures, involving 15 traders across two desks.[12] Separately, JPMorgan operates the largest COMEX-registered gold and silver depositories in the United States, and its vault holdings are reported publicly in COMEX depository reports.[13] Whether the bank accumulated physical metal while suppressing paper prices is a claim raised in private antitrust litigation and by market commentators — it is not a finding of the CFTC, DOJ, or SEC enforcement actions, and this article does not assert it as fact.[12][13]
One rail protects the deposit relationship. The other attempts to challenge privately issued coins such as USDT and USDC on their own terrain. The banks are not choosing between old money and new money. They are building both.
The Repo Question
There is a persistent phrase in the debate: “outside the central bank repo.”
It is imprecise.
A private stablecoin reserve can be outside the Federal Reserve’s liability structure while still being invested in Treasury bills or qualifying overnight Treasury repo. The coin itself is not an asset in the Fed’s balance sheet. Its backing may nevertheless sit on the same broad collateral pile used throughout the Treasury financing system.[5]
The distinction matters:
- A Federal Reserve balance is a central-bank liability.
- A bank deposit is a commercial bank liability.
- A GENIUS payment stablecoin is a private issuer’s liability.
- A Treasury bill is a claim on the federal government.
- A repo is a secured financing arrangement involving collateral and counterparties.
Calling the stablecoin “outside the Fed” does not mean it is outside Treasury markets. It means the token is not central-bank money.
For a portfolio that includes precious metals, the immediate implication is not automatically bullish or a replay of the Hunt brothers’ silver episode. A successful stablecoin system could create another large buyer of short Treasuries and overnight repo: assets that compete with gold for investors seeking liquidity and real yield. If the system fails under stress, the lesson would be different but equally important: a dollar label does not eliminate legal, liquidity, custody, or counterparty risk.
Is It a Cartel?
Here the language must become disciplined.
GENIUS creates an issuer framework. It requires reserves, restricts lending, prohibits issuer-paid yield, imposes compliance obligations, and limits who may issue payment stablecoins. It does not authorize twenty-one competitors to fix prices, divide customers, or exclude rivals.[3][5]
But a joint venture among twenty-one financial institutions raises a legitimate antitrust question. The announced structure involves one new company, shared coordination, and a common product strategy. The reserve arrangement and governance model have not yet been disclosed.[1]
That could eventually look like a payment utility: shared infrastructure that lowers costs and improves interoperability. Or it could look like a private club whose members use regulatory scale to control access to the most important parts of the market.
The Visa and Mastercard analogy is useful precisely because it does not answer the question. A payments network can be indispensable infrastructure and still require scrutiny over pricing, access, governance, and conflicts of interest.
“Coordination” is documented by the joint announcement. “Collusion” is a legal conclusion that has not been established. The difference is not a technicality. It is the difference between reporting and prosecution.

The Moat Is Regulatory and Architectural
The consortium’s planned dollar-first, euro-second strategy introduces another complication. GENIUS and the European Union’s Markets in Crypto-Assets framework do not use identical reserve rules or supervisory structures.[14]
That means a serious U.S.-dollar and euro operation may require separate legal entities, separate compliance systems, and separate reserve pools: or a structure limited to the intersection of both regimes. That is an expensive burden for a small issuer. For twenty-one global institutions, it may be an entry barrier.
The public chain creates a second layer of separation. The token may move freely across a network while the reserve assets remain inside a custody and control structure governed by the issuer and its service providers. The digital claim travels. The collateral does not.
The yield ban then removes one obvious form of competition. The issuers cannot simply offer holders a higher rate for keeping the coin. They compete instead for wallets, merchants, platforms, settlement volume, and institutional customers. The coupon is centralized; the customer acquisition battle is not.
What You Should Watch
The September announcement is a blueprint, not a finished monetary instrument. The unanswered questions are more important than the branding exercise:
- What will the company and coin be called?
- Which blockchain or blockchains will be used?
- Who will control the minting and redemption keys?
- Who is legally responsible if the coin cannot be redeemed at par during a stress event?
- Who will custody the reserves?
- Will the reserve pool be shared, segregated, or allocated by institution?
- What governance rights will each member possess?
- Will access be open to competitors, or restricted to the founding club?
Those answers will determine whether this becomes useful payment infrastructure or a concentrated private claim on public collateral.
The GENIUS Act gave the banks a lane. It did not decide whether the vehicle traveling down it is a utility, a club, or a cartel. That judgment belongs to facts that have not yet been published.
The prudent approach is therefore neither panic nor applause. Treat the proposed coin as a new financial claim. Read the redemption promise. Identify the reserve custodian. Separate the private issuer from the bank deposit and the Federal Reserve balance. As with any foundation, the important question is not how polished the building looks. It is what happens when the river rises.
Sources
[3] GovInfo, Public Law 119-27, GENIUS Act
[4] Congress.gov, S. 1582, 119th Congress
[5] Congressional Research Service, “The GENIUS Act: Stablecoin Regulation,” IN12553
[8] Tether, 2025 Treasury Holdings and Attestation Reports
[9] The Clearing House, “Major Financial Institutions Unveil Bank-Led On-Chain Money Initiative”
[10] Roic News, “JPMorgan's Lake: ‘We Are Seeing Zero Demand for Deposit Tokens’,” June 9, 2026
[12] CFTC Press Release 8260-20, “CFTC Orders JPMorgan to Pay Record $920 Million for Spoofing and Manipulation,” September 29, 2020; U.S. Department of Justice, “JPMorgan Chase & Co. Agrees To Pay $920 Million in Connection with Schemes to Defraud Precious Metals and U.S. Treasuries Markets,” September 29, 2020
[13] CME Group, COMEX-approved depositories and public precious-metals depository reporting framework; CME Group, precious-metals physical delivery process and depository reporting
[14] European Securities and Markets Authority, Markets in Crypto-Assets Regulation
Disclosure
Regatta Financial LLC provides fee-only investment advisory services with no commissions on investment transactions. This article is provided for general educational and informational purposes only and does not constitute individualized investment, tax, legal, or accounting advice. Stablecoins, Treasury securities, repurchase agreements, bank deposits, and precious metals involve different legal, liquidity, market, custody, and counterparty risks. You should consult qualified professionals regarding your own circumstances. Past performance is not indicative of future results.
Confidence statement: High confidence in the enacted GENIUS Act framework, its reserve and insurance provisions, the January 2025 executive order, and The Clearing House’s tokenized-deposit initiative. Moderate confidence in the reported September 1 consortium details because the planned issuer, blockchain, reserve structure, governance, and redemption arrangements had not been publicly finalized as of September 14, 2026. The antitrust discussion is analysis, not a finding of collusion.
Leave a Reply